Contractor Commercial Auto Insurance in WA, OR & ID
Protect your business with Commercial Auto, General Liability, Workers' Compensation, Inland Marine, and Contractor Bonds tailored for contractors throughout the Pacific NW.
Contractor Commercial Auto Insurance in WA, OR & ID
Protect your business with Commercial Auto, General Liability, Workers' Compensation, Inland Marine, and Contractor Bonds tailored for contractors throughout the Pacific NW.
Why Contractors Need Commercial Auto Insurance
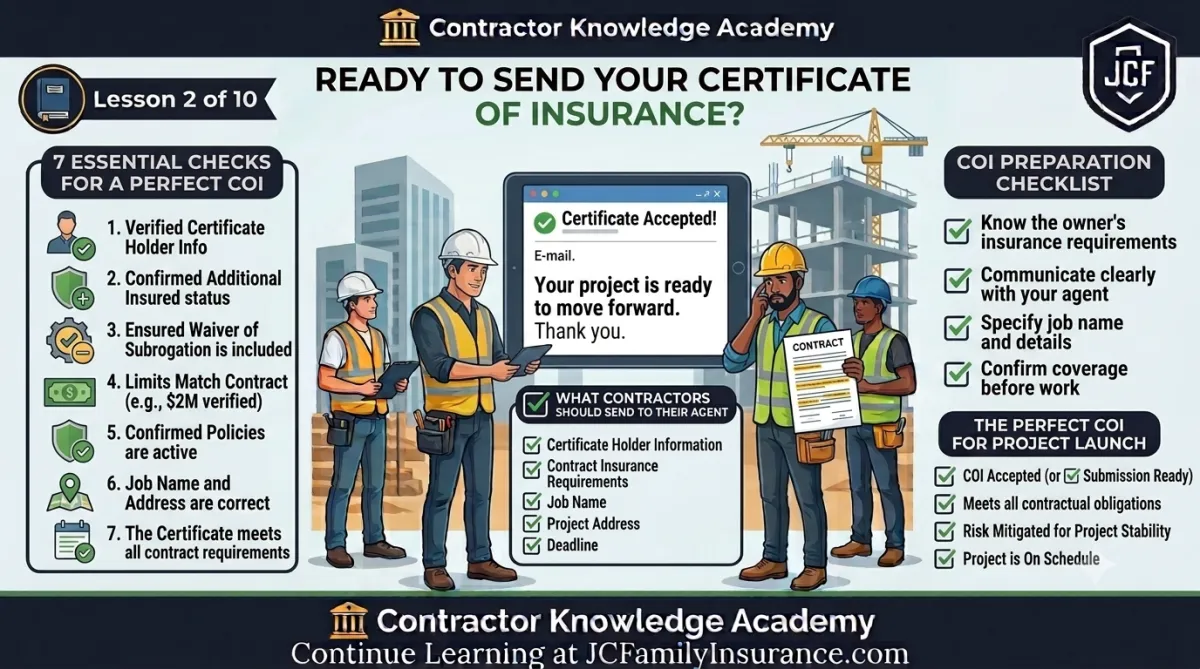
Contractors face unique risks every day. From property damage claims and employee injuries to equipment theft and rejected certificates of insurance, one unexpected loss can delay projects and impact profitability.We help contractors secure coverage that meets contract requirements while protecting their business, employees, vehicles, and equipment.
Additional Coverage Options for Contractors
General Liability
Helps Protect Your Business From
Third Party Bodily Injury
Property damage claims
Completed operations claims
Legal defense costs
Commercial Auto Insurance
Coverage For
Work Trucks
Dump Trucks
Trailers
Company Vehicles
Workers' Compensation
Protection For Employee's
Medical Expenses
Lost Wages
Workplace Injuries
Satisfy State Requirements
Inland Marine Insurance
Helps Protect Your Business From
Excavators
Skid Steers
Trailers
Tools & Machinery
Common Risks
Contractors Face
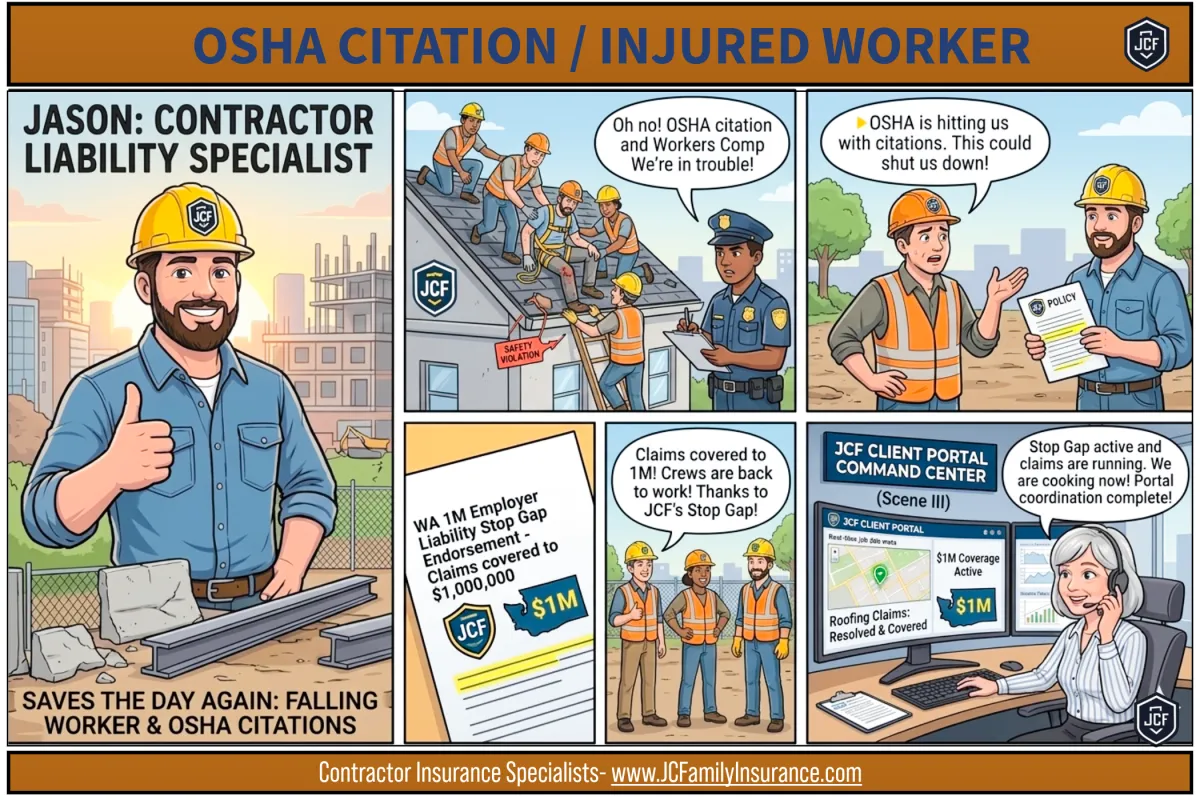
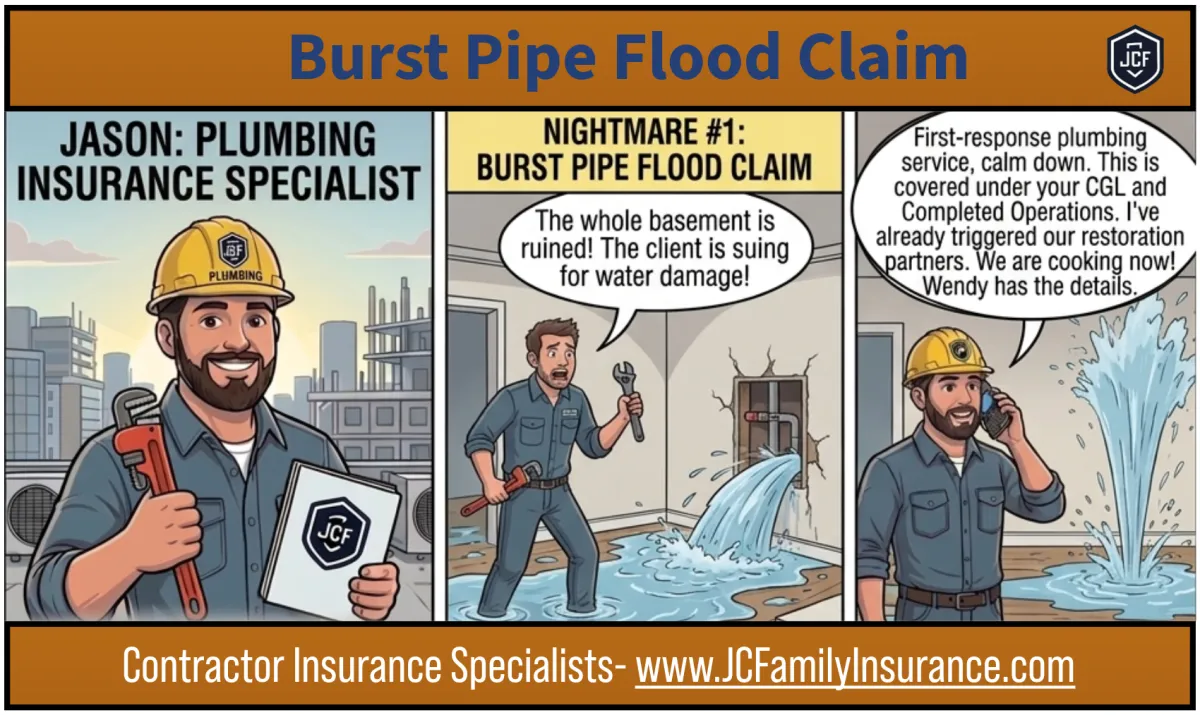
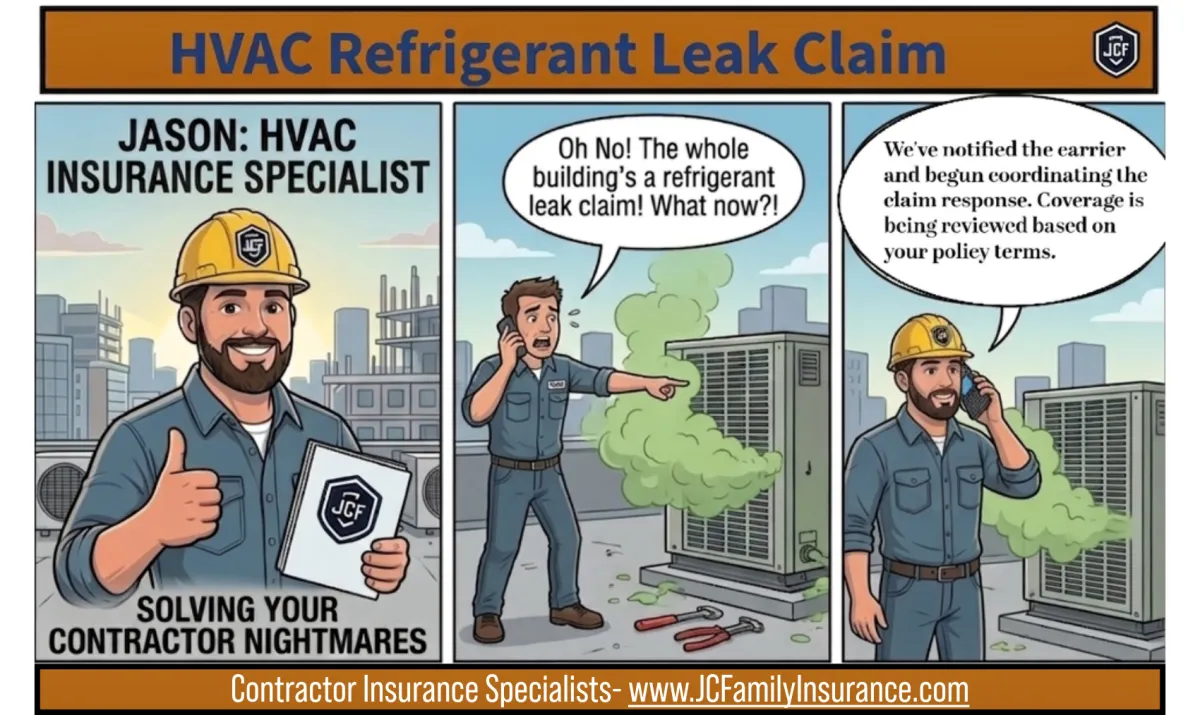
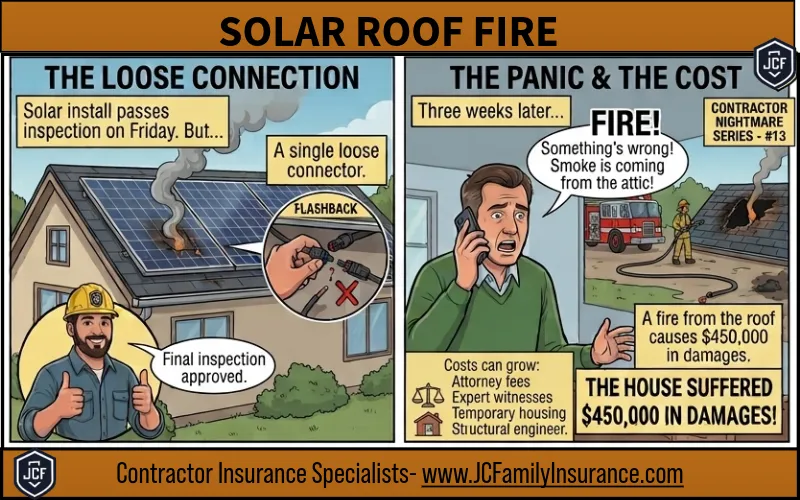
Explore More Contractor Nightmares
Why Contractors Choose JC Family Insurance
Insurance Built for Contractors, Not Just Businesses
Whether you're just starting your company or managing multiple crews across Washington, Oregon, or Idaho, your insurance should work as hard as you do. We combine contractor expertise with modern technology to make quoting, buying, and managing your policies faster and easier.
🏗️ Contractor Specialists
Construction insurance is our specialty. We understand contractor licensing requirements, certificates of insurance, additional insured requests, commercial auto, surety bonds, workers' compensation, and the coverages contractors need to stay compliant and win more jobs.
🔍 Multiple Companies. More Choices.
As an independent insurance agency, we compare coverage and pricing from multiple insurance companies—not just one. That means you can review your options and choose the policy that best fits your business and budget.
⚡ Shop, Select & Buy Online
Request a quote, upload documents, sign electronically, make secure payments, and complete more of the insurance process online—without unnecessary office visits.
📂 24/7 Online Policy Center
Access your policies anytime through our secure Policy Center. View documents, download certificates, request policy changes, make payments, and keep everything organized in one convenient place.
💳 Easy Payments & Premium Financing
Pay your way with secure online payments and flexible premium financing options. Monthly payment plans, convenient payment links, and mobile-friendly tools help make managing your insurance simple.
📚 Free Contractor Resources
We're more than an insurance agency. Our Contractor Resource Center includes licensing guides, contractor education, safety resources, industry updates, and our popular Contractor Nightmares series designed to help you avoid costly mistakes before they happen.
The JC Family Insurance Advantage
Modern tools. More options. Real contractor expertise.
Typical Insurance Experience
Limited Market Options
Phone-First & Fragmented Service
Documents Buried In Emails
Limited Payment Flexibility
Generalist Insurance Approach
Limited Contractor Education & Resources
JC Family Insurance
Compare Available Quote Options From Multiple Carriers
24/7 Digital Tools + Direct Human Support
Secure Online Policy & Document Center
Online Payments, Financing & Carrier Payment Access
Contractor-Focused Insurance & Surety Specialists
Licensing Guides, Bond Education, Contractor Resources & Real-World Claim Lessons
Get a Contractor Insurance Quote
Whether you're a new contractor or reviewing your current coverage, we
can help you compare options and identify potential coverage gaps.
The JC Family Insurance Advantage
Typical Insurance Experience
Limited Market Options
Phone-First & Fragmented Service
Documents Buried In Emails
Limited Payment Flexibility
Generalist Insurance Approach
Limited Contractor Education & Resources
JC Family Insurance
Compare Available Quote Options From Multiple Carriers
24/7 Digital Tools + Direct Human Support
Secure Online Policy & Document Center
Online Payments, Financing & Carrier Payment Access
Contractor-Focused Insurance & Surety Specialists
Licensing Guides, Bond Education, Contractor Resources & Real-World Claim Lessons
Get a Contractor Insurance Quote
Whether you're a new contractor or reviewing your current coverage, we
can help you compare options and identify potential coverage gaps.
Find Insurance Resources for Your Contractor Trade
Find Insurance Resources for Your Contractor Trade
Contractor insurance is not one-size-fits-all. Select your trade below to explore common coverage needs, industry-specific risks, and insurance considerations for the work your business performs.
Contractor insurance is not one-size-fits-all. Select your trade below to explore common coverage needs, industry-specific risks, and insurance considerations for the work your business performs.
Explore Contractor Insurance By Trade
Find insurance solutions tailored to your trade. We help contractors across Washington, Oregon, and Idaho secure general liability, commercial auto, workers compensation, inland marine, and contractor bond coverage.
Don't see your trade listed? We insure nearly every licensed contractor trade in Washington, Oregon & Idaho. Get a fast quote today.
Don't see your trade? We insure nearly every licensed construction trade in the Pacific NW - Serving All of Washington, Oregon & Idaho.
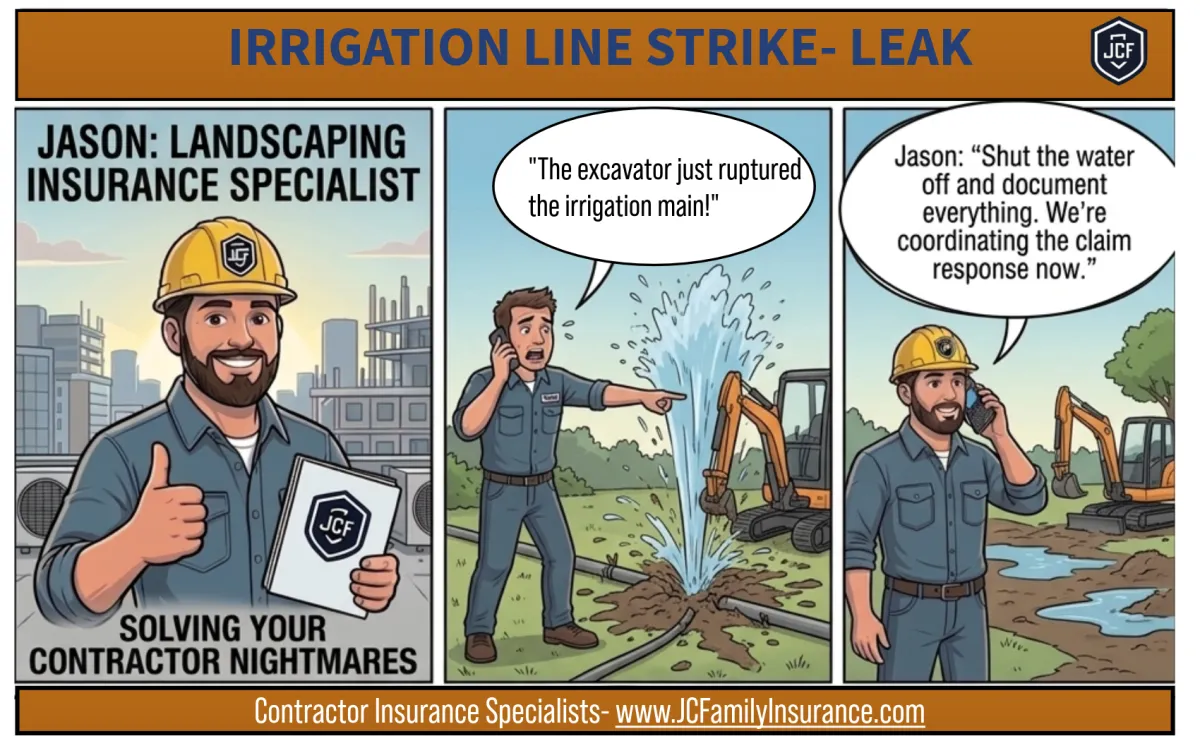
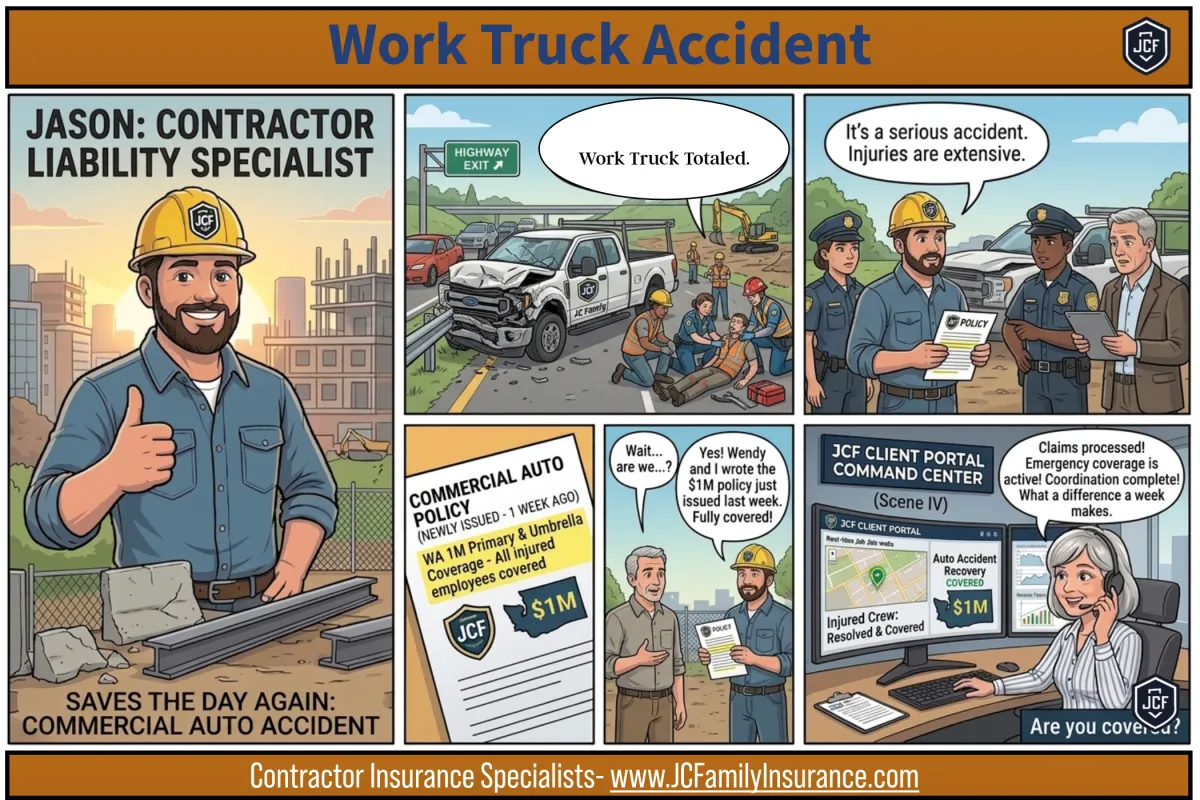
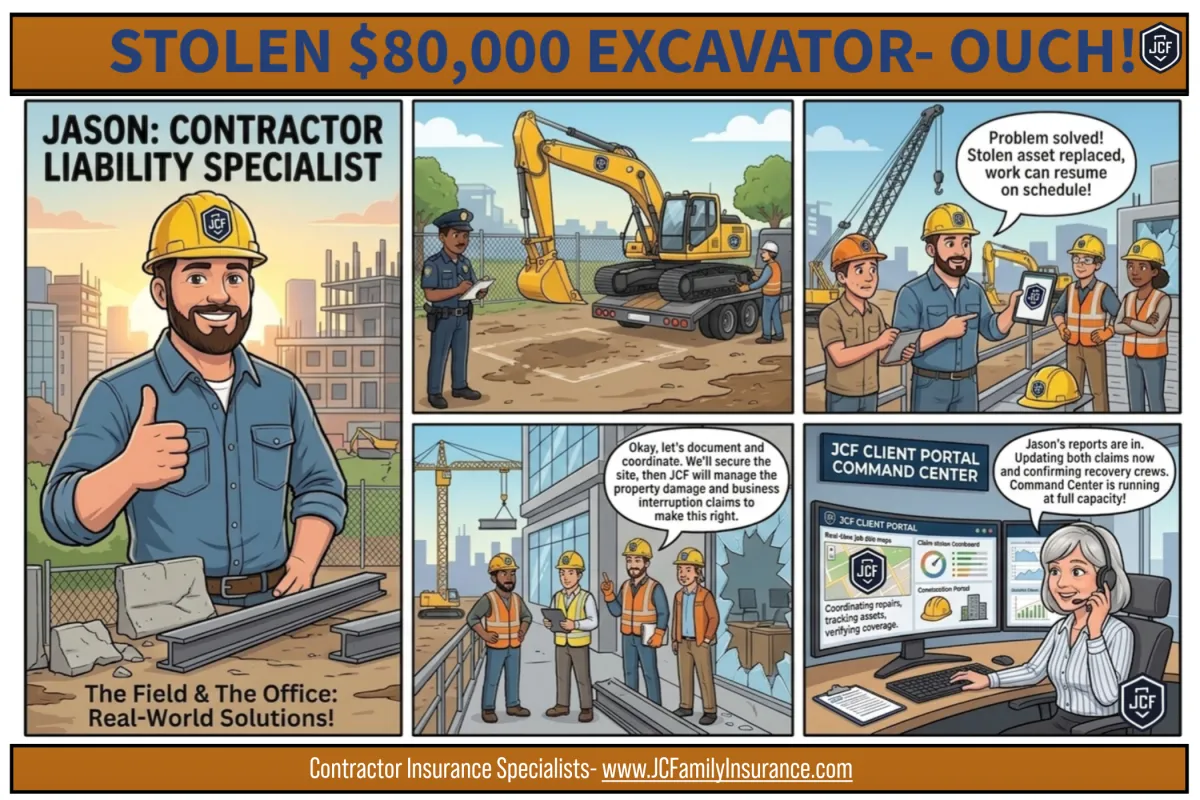
Explore Our Contractor Nightmares Series
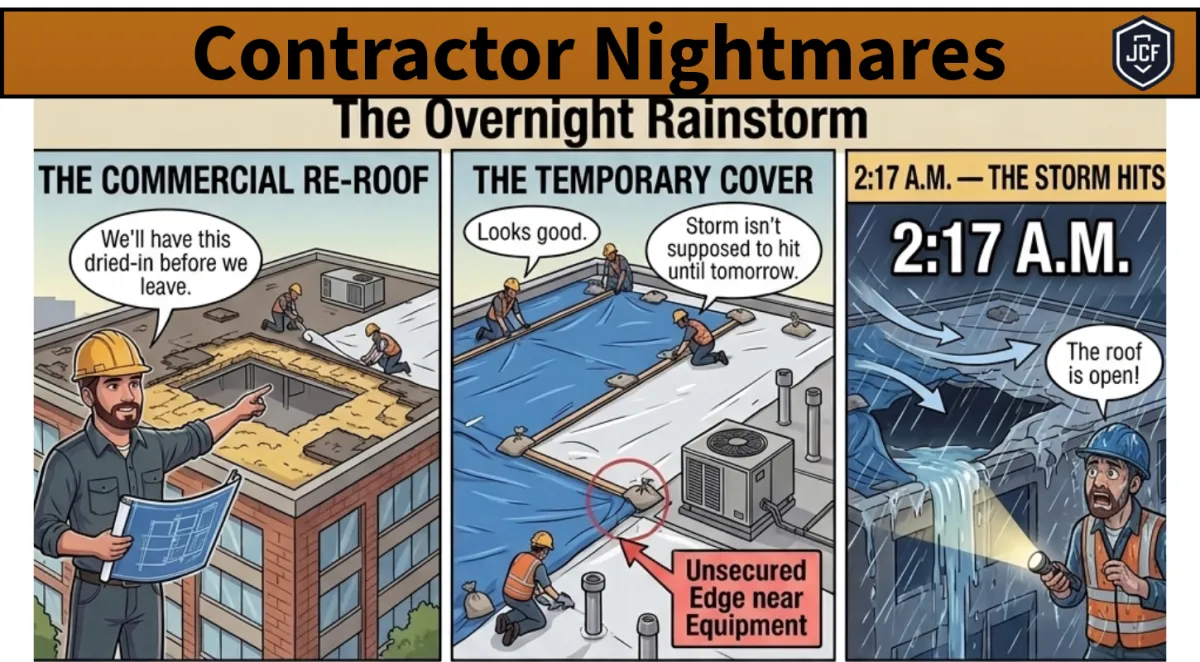
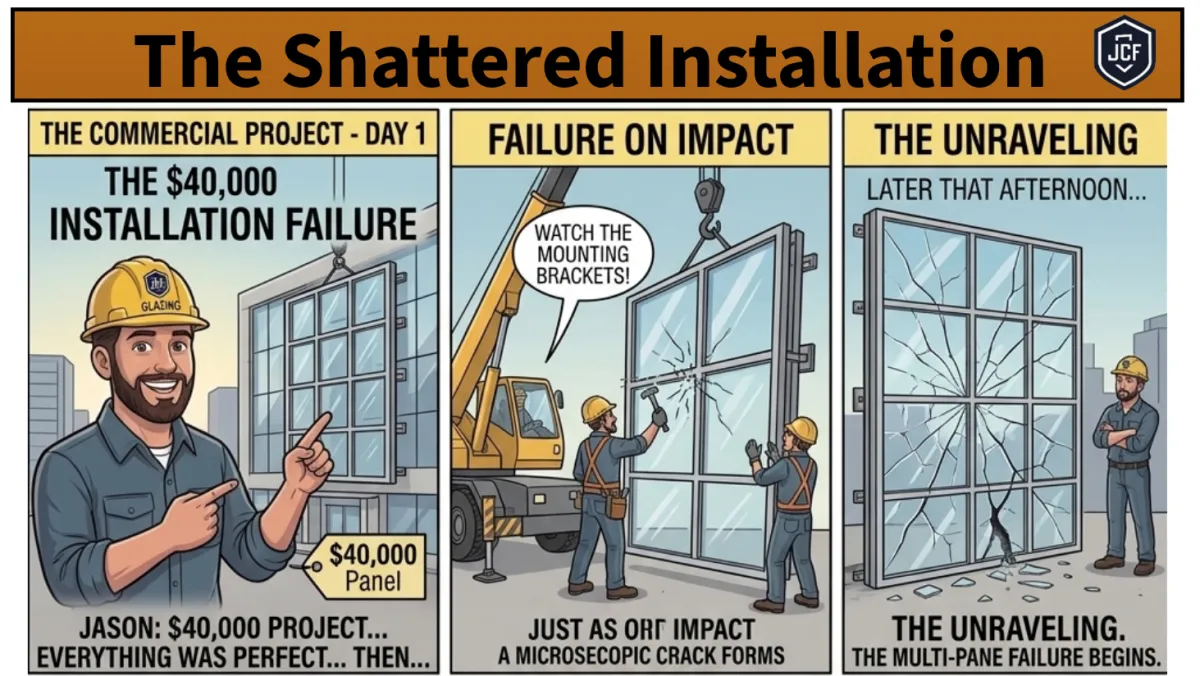
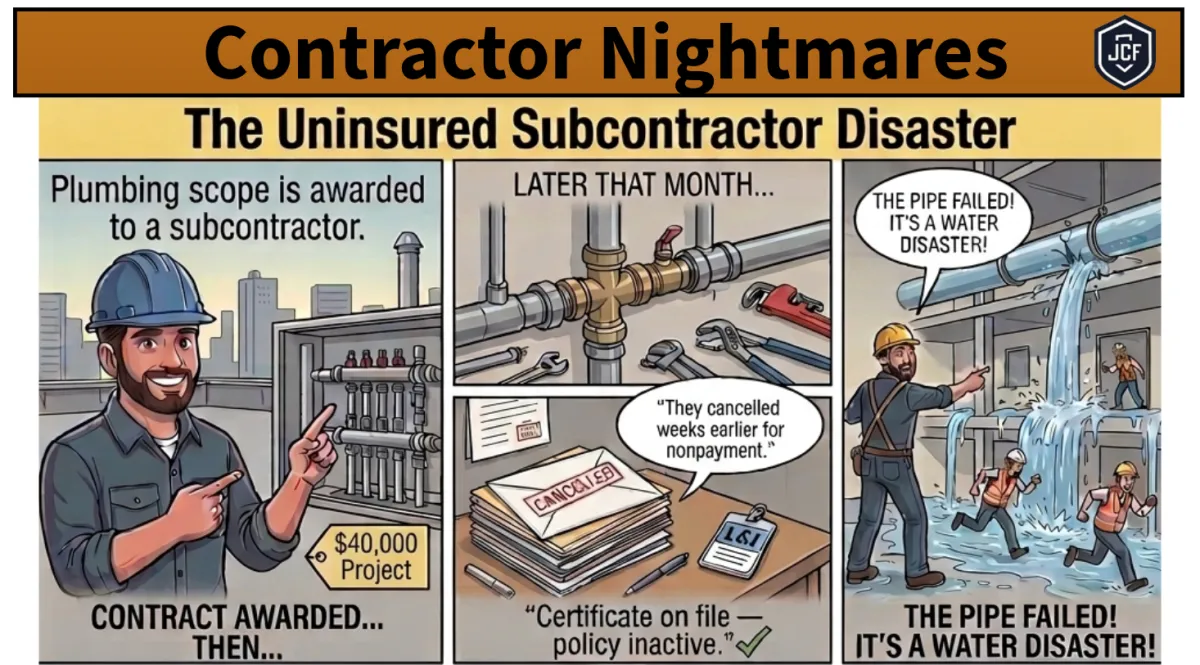
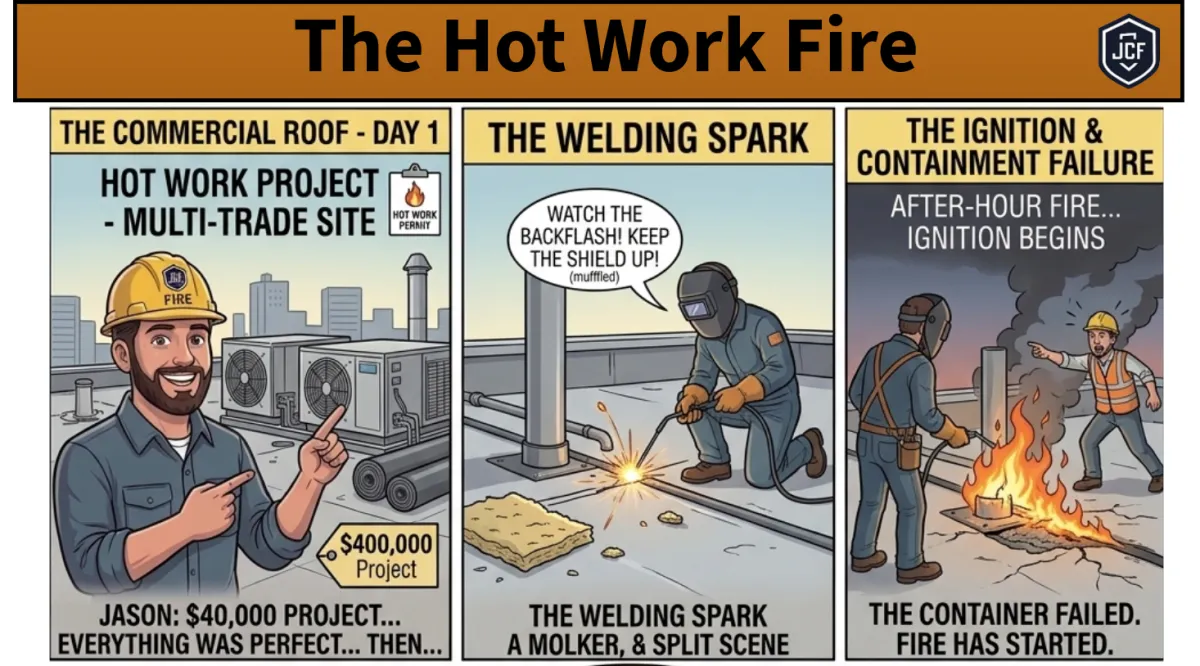
Common Risks Contractors Face — Real-World Claim Scenarios Explained in Our Contractor Nightmares Series
Irrigation Line
Strike
Work Truck
Accident
Stolen
Excavator
OSHA
Citation
BAD
Certificate
Bond
Rejected
Burst Pipe
Flood Claim
The Overnight Rainstorm
The Shattered
Installation
The Uninsured
Subcontrator
The Hot Work
Fire
Refrigeration Line
Leak
COMING SOON
COMING SOON
COMING SOON
The Loose Connection
COMING SOON
COMING SOON
Get a Contractor Insurance Quote
Whether you're a new contractor or reviewing your current coverage, we can help you
compare options and identify potential coverage gaps.
Common questions answered
Answers to Frequently Asked Questions
Do All Contractors need Commercial Auto Coverage?
In most situations, businesses with company owned vehicles are required to carry commercial auto coverage.
How much does Contractor Commercial Auto Insurance cost?
Costs vary based on payroll, subcontractor costs, revenue, claims history, and the type of work performed.
What does commercial auto insurance cover?
Commercial auto insurance can cover liability for bodily injury and property damage caused by vehicles used for business. Depending on the policy, coverage may also include collision, comprehensive, uninsured/underinsured motorists, medical payments, hired and non-owned auto, and other business-specific protections.
Can my employees drive vehicles insured on my commercial auto policy?
Employees can often be covered when driving insured company vehicles with permission, but driver eligibility and coverage depend on the carrier and policy. Insurers may review each driver's license and driving history.
Does commercial auto insurance cover tools and equipment inside my truck?
Usually not automatically. Commercial auto primarily insures the vehicle and auto-related liability. Tools and equipment may require inland marine, contractor's equipment, or another form of property coverage.
What is hired and non-owned auto insurance?
Hired and non-owned auto coverage can protect a business from certain liability exposures when vehicles the business doesn't own are used for company business, such as rented vehicles or employees using their personal vehicles for work.
Does commercial auto insurance cover trailers?
Coverage depends on the trailer and how it is used. Some liability protection may extend from the towing vehicle, but physical damage coverage for an owned trailer may need to be specifically added. Contractors should also consider coverage for equipment or materials being transported.
What information do I need to get a commercial auto insurance quote?
Typically, you'll need information about your business, vehicle VINs, vehicle use, garaging locations, estimated mileage, driver names and license information, current coverage, and prior loss history. Having your current policy available can make quoting considerably faster.
Why is commercial auto insurance more expensive than personal auto insurance?
Business vehicles often spend more time on the road, travel to multiple locations, carry equipment, and can create greater liability exposure than a typical personal vehicle. Vehicle type, radius, driver records, coverage limits, claims history, and business operations all affect pricing.
Does my personal auto insurance cover my pickup truck if I use it for my contracting business?
Not necessarily. Even if a pickup is personally titled, regular business use can create coverage issues under a personal auto policy. Driving to job sites, hauling tools or materials, towing work trailers, or allowing employees to drive the vehicle can change the exposure. A commercial auto policy may be the appropriate solution.
Can contractors insure work trucks and vans under commercial auto insurance?
Yes. Commercial auto insurance is commonly used for contractor pickups, cargo vans, service vans, utility vehicles, and other vehicles used to travel between job sites or transport equipment and materials.
Can I insure multiple work trucks on one commercial auto policy?
Yes. Businesses can generally insure multiple vehicles under one commercial auto policy. As your company adds or replaces vehicles, the policy can usually be updated rather than purchasing a completely separate policy for every vehicle.
How much commercial auto liability insurance should my business carry?
The right limit depends on your operations, vehicles, contracts, and overall risk. Many businesses carry at least $1 million in commercial auto liability, while some contracts or operations may require higher limits or a commercial umbrella/excess liability policy.
Can I get commercial auto insurance with drivers who have tickets or accidents?
Often, yes, although driving records can affect which insurance companies will offer coverage and what the policy costs. Serious violations, multiple accidents, or inexperienced drivers can significantly reduce available options.
Can commercial auto insurance cover vehicles in Washington, Oregon, and Idaho?
Yes. JC Family Insurance helps businesses obtain commercial auto coverage in Washington, Oregon, and Idaho, including contractors with vehicles operating across multiple states.
Can you insure commercial auto along with general liability and workers' compensation?
Yes. Businesses can often coordinate commercial auto with general liability, workers' compensation, inland marine, commercial umbrella, and other coverage. Policies do not necessarily have to be written with the same insurance company.
How quickly can I get a commercial auto insurance quote?
Simple accounts can sometimes be quoted quickly once complete vehicle and driver information is available. Larger fleets, specialized vehicles, interstate operations, or businesses with more complex loss histories may require additional underwriting.
Want to work with us?
Get contractor insurance, bonds, and certificates from a local team that understands how your business works.
CONTRACTOR INSURANCE
INSURANCE BY TRADE
CONTRACTOR RESOURCES
TOOLS & POLICY CENTER
ABOUT JCF
GET HELP
WA · OR · ID · AZ · GA
CONTACT INFORMATION
(971) 412-4469
9020 SW Washington Sq Rd Portland, OR 97223
CONNECT WITH JCFAMILY INSURANCE
FOLLOW & REVIEW US ONLINE